
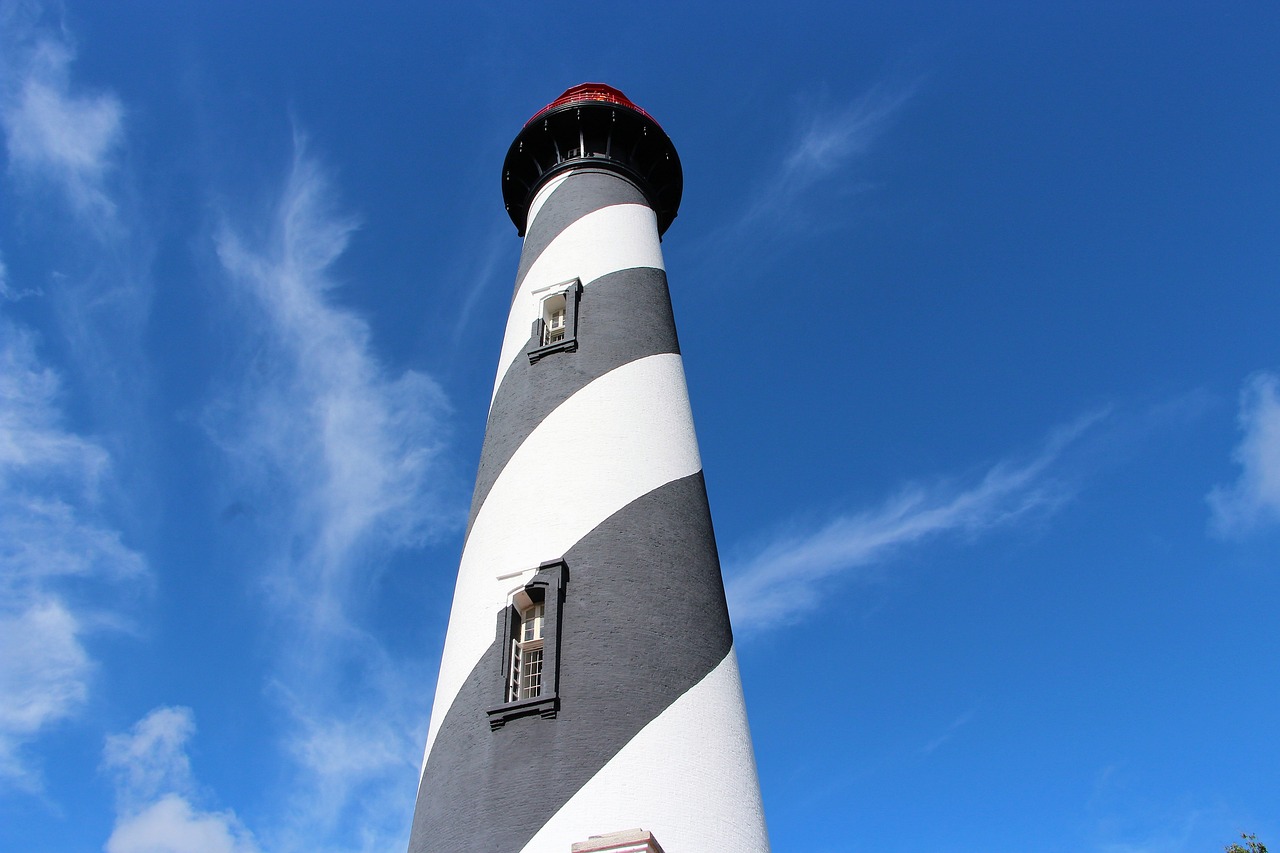
Getting a St. Augustine mortgage works much like buying anywhere else in Florida, but the city’s older homes, coastal flood zones and condo-heavy beach areas add a few extra steps. Expect a lender to look closely at the property itself: the roof, the age of major systems, the flood zone, insurance availability and, for condos, the health of the association. Knowing those pieces early helps you write a stronger offer and avoid surprises after you go under contract.
Our office sits just down A1A in Flagler Beach, and plenty of the buyers we talk with are weighing St. Augustine, St. Augustine Beach and the communities in between. Here is what tends to come up.
Loan options St. Augustine buyers often consider
The same core programs are available in St. Johns County as in the rest of Florida. Which one fits depends on your credit, income, savings and the home you choose. Requirements vary by program and lender, and a lender will review your full file.
- Conventional loans are common for primary homes, second homes and investment property. Smaller down payments usually come with private mortgage insurance.
- FHA loans can help buyers with smaller down payments or credit that is still being rebuilt. The home must meet FHA property standards, which matters with older houses.
- VA loans are worth a close look for eligible veterans and service members, especially with the military presence across northeast Florida.
- USDA loans may apply to eligible properties in certain areas outside the more developed parts of the county. Eligibility maps change, so check the specific address.
- Jumbo loans come into play for higher priced homes near the water or in some newer communities.
- Renovation loans can roll certain repair or improvement costs into the mortgage, which can help with a dated or older home.
Financing older and historic homes
Character is a big part of why people fall for St. Augustine. Older homes can be wonderful to own, but they get extra attention from appraisers, inspectors and insurers. A few things to plan for:
- Roof age and condition. Many Florida insurers look hard at roof age, and some will not write a new policy on an older roof without updates.
- Electrical, plumbing and HVAC. Older wiring types and aging plumbing materials can affect insurance options and sometimes the appraisal.
- The 4-point inspection. Insurers commonly ask for one on older homes. It covers the roof, electrical, plumbing and HVAC, and the results can shape your premium.
- Appraisal comparables. Unique homes can be harder to compare. Appraisers may need to reach further for similar sales, which can take a little longer.
- Renovation plans. If the home is in a designated historic area, exterior changes may need city review. Check with the city before you count on a specific renovation in your budget.
If you are buying an older home, ask your agent about inspection timing so the 4-point and any wind mitigation report are done early in your contract period. Our guide to wind mitigation and 4-point inspections for Florida buyers explains how those reports work.
Flood zones and insurance near the water
St. Augustine is surrounded by water: the Matanzas River, the San Sebastian River, marshes and the ocean. Flood zones can change from one street to the next. If a home sits in a high-risk flood zone and you use a federally backed or regulated mortgage, flood insurance will generally be required. Even outside those zones, many buyers choose to carry it.
Homeowners and wind coverage are the other big pieces. Together they can make a meaningful difference in your monthly payment and in how much you need at closing, since the first year’s premium and an escrow cushion are usually collected up front. A few habits help:
- Ask the seller for any existing elevation certificate and wind mitigation report.
- Get insurance quotes during your inspection period, not the week before closing.
- Keep in mind that insurers may pause new policies when a named storm is approaching.
- Run your payment with realistic insurance numbers using our mortgage calculator.
Condos and HOA communities
From Anastasia Island to the newer planned communities west of the city, a lot of St. Johns County living comes with an association. That affects financing in two ways. First, monthly dues count in your debt to income ratio. Second, for condos, the lender reviews the building and the association, not only you.
Lenders may ask about reserves, pending special assessments, insurance coverage, litigation, owner occupancy and recent inspections. Florida’s condo safety rules have pushed many coastal associations to complete structural reviews and build up reserves, which can mean higher dues or special assessments. Ask for the association documents early. Our Florida condo financing checklist covers what to request before you make an offer.
Second homes and rental plans
St. Augustine draws many buyers looking for a getaway or a property to rent out. How you plan to use the home matters to the lender. A second home is generally one you use yourself for part of the year and do not run as a full time rental. A property bought mainly for rental income is usually financed as an investment property, which often means a larger down payment and different requirements.
Be upfront about your plans from the start. Short term rental rules also vary by city, county and association, so confirm what is allowed before you count on rental income.
Taxes and closing in St. Johns County
Closing costs in St. Johns County follow the same general pattern as the rest of Florida: lender charges, title and settlement fees, state documentary stamp and intangible taxes on the mortgage, recording fees and prepaid items like insurance, interest and escrow. Your Loan Estimate shows your specific figures.
Property taxes are paid in arrears, and the seller’s bill may reflect their own homestead exemption. Your future taxes will be based on a new assessment. If the home will be your primary residence, you can apply for the homestead exemption with the St. Johns County Property Appraiser after you buy. This is general information, not tax advice.
Frequently asked questions
Do I need a local lender to buy in St. Augustine?
You can use any properly licensed lender. A loan officer who knows northeast Florida can help you anticipate insurance, flood and condo questions that tend to come up with coastal and older properties.
Can I get an FHA loan on an older home?
Often, yes, as long as the home meets FHA property standards. If repairs are needed, they may have to be completed before closing, or a renovation loan may be an option. A lender will review the appraisal and the property’s condition.
Is flood insurance always required in St. Augustine?
No. It is generally required when the home is in a high-risk flood zone and the loan is federally backed or regulated. Outside those zones it is usually optional, though many coastal owners carry it anyway.
How early should I talk to a lender?
Before you start touring seriously. A preapproval tells you your price range and gives sellers confidence, and an early conversation gives you time to sort out credit, savings or documents.
If St. Augustine is on your list, Michael Akialis is happy to talk through your options from our office on South Central Avenue in Flagler Beach. He has worked in local real estate and lending for more than two decades, including years at a title company before becoming a loan officer. Read more about Michael, browse more Florida mortgage guidance, or call (386) 793-5435.
Mortgage information is for educational purposes only and is not a commitment to lend or extend credit. All loans are subject to credit approval, property approval, underwriting guidelines, program eligibility, and availability. Program rules, rates, fees, and requirements can change. Michael Akialis, NMLS #832250; American Home Mortgage Group LLC, NMLS #1812447.